The donation most people forget they can make
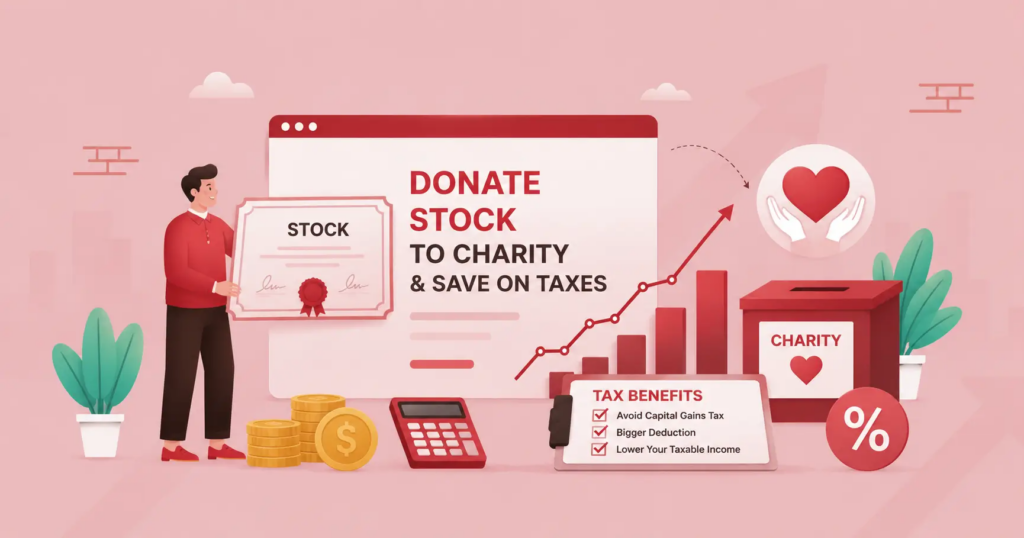
When most people think about donating, they think about writing a check or clicking a donate button. But if you’re an investor sitting on stock, mutual funds, or ETFs that have gone up significantly since you bought them, there’s a more tax-efficient way to give, and most donors have never been told about it.
It’s not a loophole or an aggressive tax strategy. It’s a well-established, IRS-recognized way of giving that happens to benefit the donor almost as much as the charity. The only reason it’s underused is that nobody mentions it at the moment people are deciding how to give.
How giving stock beats giving cash
Say you bought shares years ago for $5,000, and today they’re worth $25,000. If you sell them yourself, you owe long-term capital gains tax on the $20,000 gain, typically 15% or 20% depending on your income, plus an additional 3.8% net investment income tax if you’re above certain income thresholds. Depending on your bracket, that can mean handing $4,000-$5,000 or more to the IRS before you ever get to decide what to do with the rest.
Donate the same shares directly to a qualifying charity instead, and none of that tax is ever triggered. The charity can sell the stock and keep the full $25,000, not $25,000 minus your capital gains bill. You gave more, the IRS collected nothing on the transaction, and you never had to come up with the cash yourself.
The deduction most donors miss
There’s a second benefit stacked on top of avoiding the capital gains tax. If you itemize your deductions and you’ve held the stock for more than a year, you can typically deduct its full fair market value on the day you donate it , not just what you originally paid for it.
Using the same example: donate that $25,000 in stock, and you may be able to claim a $25,000 charitable deduction, even though your original cost basis was only $5,000. You’re deducting value you never paid tax on receiving in the first place, on top of avoiding the tax you would have owed for realizing the gain.
One nuance worth knowing: recent changes to charitable deduction rules introduced a floor for itemizers , your qualified charitable contributions generally need to exceed a small percentage of your adjusted gross income before the deduction kicks in. It’s a detail your tax preparer will already be aware of, but it’s part of why the exact benefit varies by donor rather than being a flat rule.
What if you’ve held the stock less than a year?
The full fair-market-value deduction only applies to stock held longer than one year (long-term capital gain property). If you’ve held it for less time, the deduction is generally limited to your cost basis, what you originally paid, rather than the current value. The capital-gains-avoidance benefit still doesn’t apply the same way either, since short-term gains are taxed as ordinary income. In practice, this strategy is most powerful for stock you’ve held for years, not something you bought last quarter.
Donor-advised funds: the flexible version
If you’d rather not choose the exact recipient the moment you give, gifting appreciated stock into a donor-advised fund gets you the same tax treatment with considerably more flexibility. You transfer the shares, take the deduction in that tax year, and then decide later, over months or years, how to distribute the funds. You can also split a single stock gift across multiple causes instead of committing it all to one place at once.
This is a common approach for donors who know they want to give but haven’t finalized exactly how much should go where. The tax event happens once, at the time of transfer; the giving decisions can happen gradually afterward.
The alternative: holding for heirs instead
Not every appreciated stock needs to be given away during your lifetime. If you don’t need the money and aren’t ready to part with a particular holding, you can also simply let it continue to grow and pass it to your heirs. When you die, the asset typically gets a “step-up” in cost basis to its value on the date of death, meaning your heirs may only owe capital gains tax on appreciation that happens after they inherit it, not on the decades of growth that happened while you held it.
This isn’t a charitable strategy, but it’s worth knowing as the comparison point: appreciated stock is valuable enough, tax-wise, that what you do with it, give it away now, or hold it for heirs later, is worth an actual decision rather than a default.
What this means if you’re funding a Lakshya Scholarship
For donors who’ve held tech stock, index funds, or other positions for years and are sitting on substantial unrealized gains, donating shares is often a more efficient way to fund a scholarship than writing a check for the same dollar amount. You give more, you keep more of your own money out of the IRS’s hands, and you avoid a tax bill you might otherwise owe anyway when you eventually sold.
If this is something you’re considering, reach out to us directly so we can walk through how to transfer the shares , the process is a short form with your broker, not a complicated legal transaction.
A rough sense of the process
- Contact your brokerage and ask for a “charitable stock transfer” or “gift of securities” form , most major brokerages have one.
- Provide the receiving charity’s account details, which the charity’s finance contact can supply.
- Specify the security and number of shares , do not sell the stock first, since that triggers the very tax event you’re trying to avoid.
- Get written acknowledgment from the charity once the shares arrive, including the transfer date and share count, for your tax records.
- Give your tax preparer the acknowledgment and the original purchase date/cost basis, even though the deduction is based on fair market value , they’ll want the full picture.
The fine print
Tax rules around charitable giving change, and your specific situation , income level, how long you’ve held the stock, whether you itemize, which deduction floors currently apply , changes the math. This isn’t tax advice, and a CPA or financial advisor can confirm exactly what applies to your return before you transfer anything.